 01
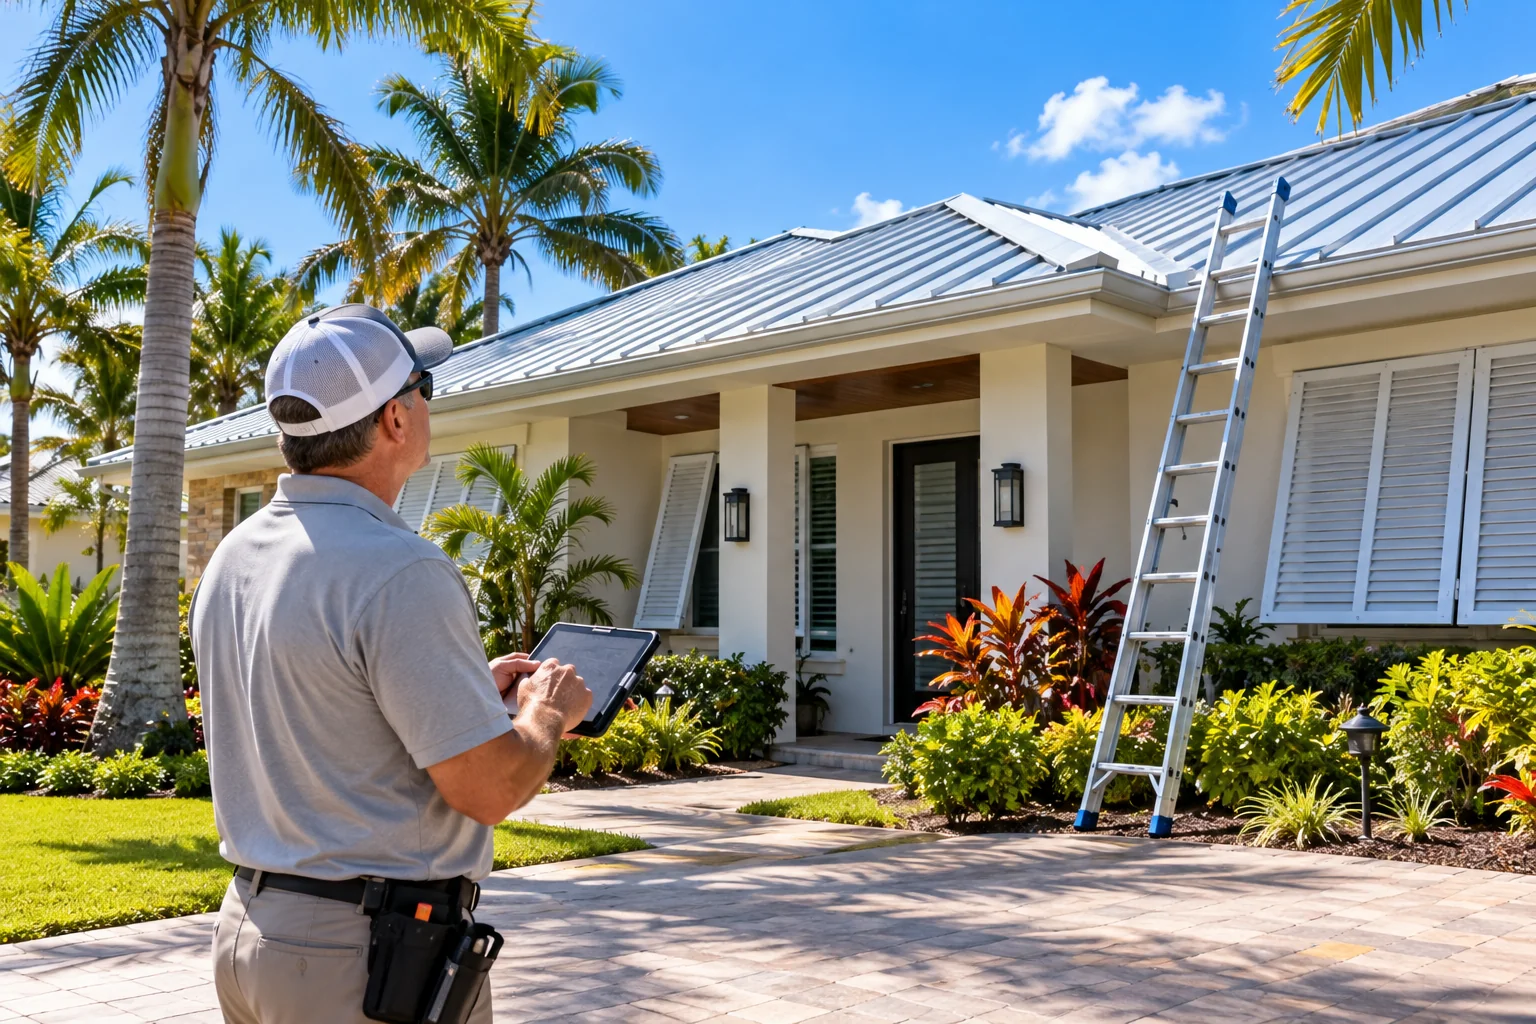
What are wind mitigation and 4-point inspections, and why do they matter?
Both are reports an insurer reads before it prices or accepts a home.
Read the answer →Ask 1stFlorida
The state's emergency managers say to protect the places where wind can get in: the roof, the roof-to-wall straps, the windows, the doors and the garage door.
Windows and doors should be impact-resistant or have a protective covering, such as rated hurricane shutters or properly secured 5/8-inch plywood. Flood damage is usually not covered by a homeowners policy.
Florida law requires home insurers to give actuarially reasonable discounts or credits for features that cut wind losses, and to tell policyholders what discounts are available and their range; a wind mitigation inspection on the state's uniform form shows which features a home has.
My Safe Florida Home, the state program, can pay part of the cost. For a site-built, owner-occupied homestead insured for $700,000 or less and built before January 1, 2008, the state puts up $2 for each $1 from the owner, up to $10,000, toward doors, garage doors, windows, roof-to-wall connections, the roof deck, a secondary water barrier and, since a 2026 law, roof covering replacement; that law also opened the program to attached homes up to three stories. Low-income owners pay no match, and low-income owners 60 and older are served first. Grants depend on what the Legislature provides each year, and a home can get the inspection without qualifying for a grant. Since 2024 a homeowners association may not deny shutters, impact windows, reinforced garage doors or a generator that meet the board's specifications.
A generator keeps the power on, but run it only outdoors, far from windows, doors and vents, never in a garage or other enclosed space; put battery-operated carbon monoxide detectors in the home; store fuel safely; and let the generator cool at least 20 minutes before refueling.
01Both are reports an insurer reads before it prices or accepts a home.
Read the answer → 02
Hurricane wind is the main cost in a Florida home policy, and the price is set by the address, the age and shape of the roof and how the house is built, so it can differ a great deal between two homes on the same street.
Read the answer →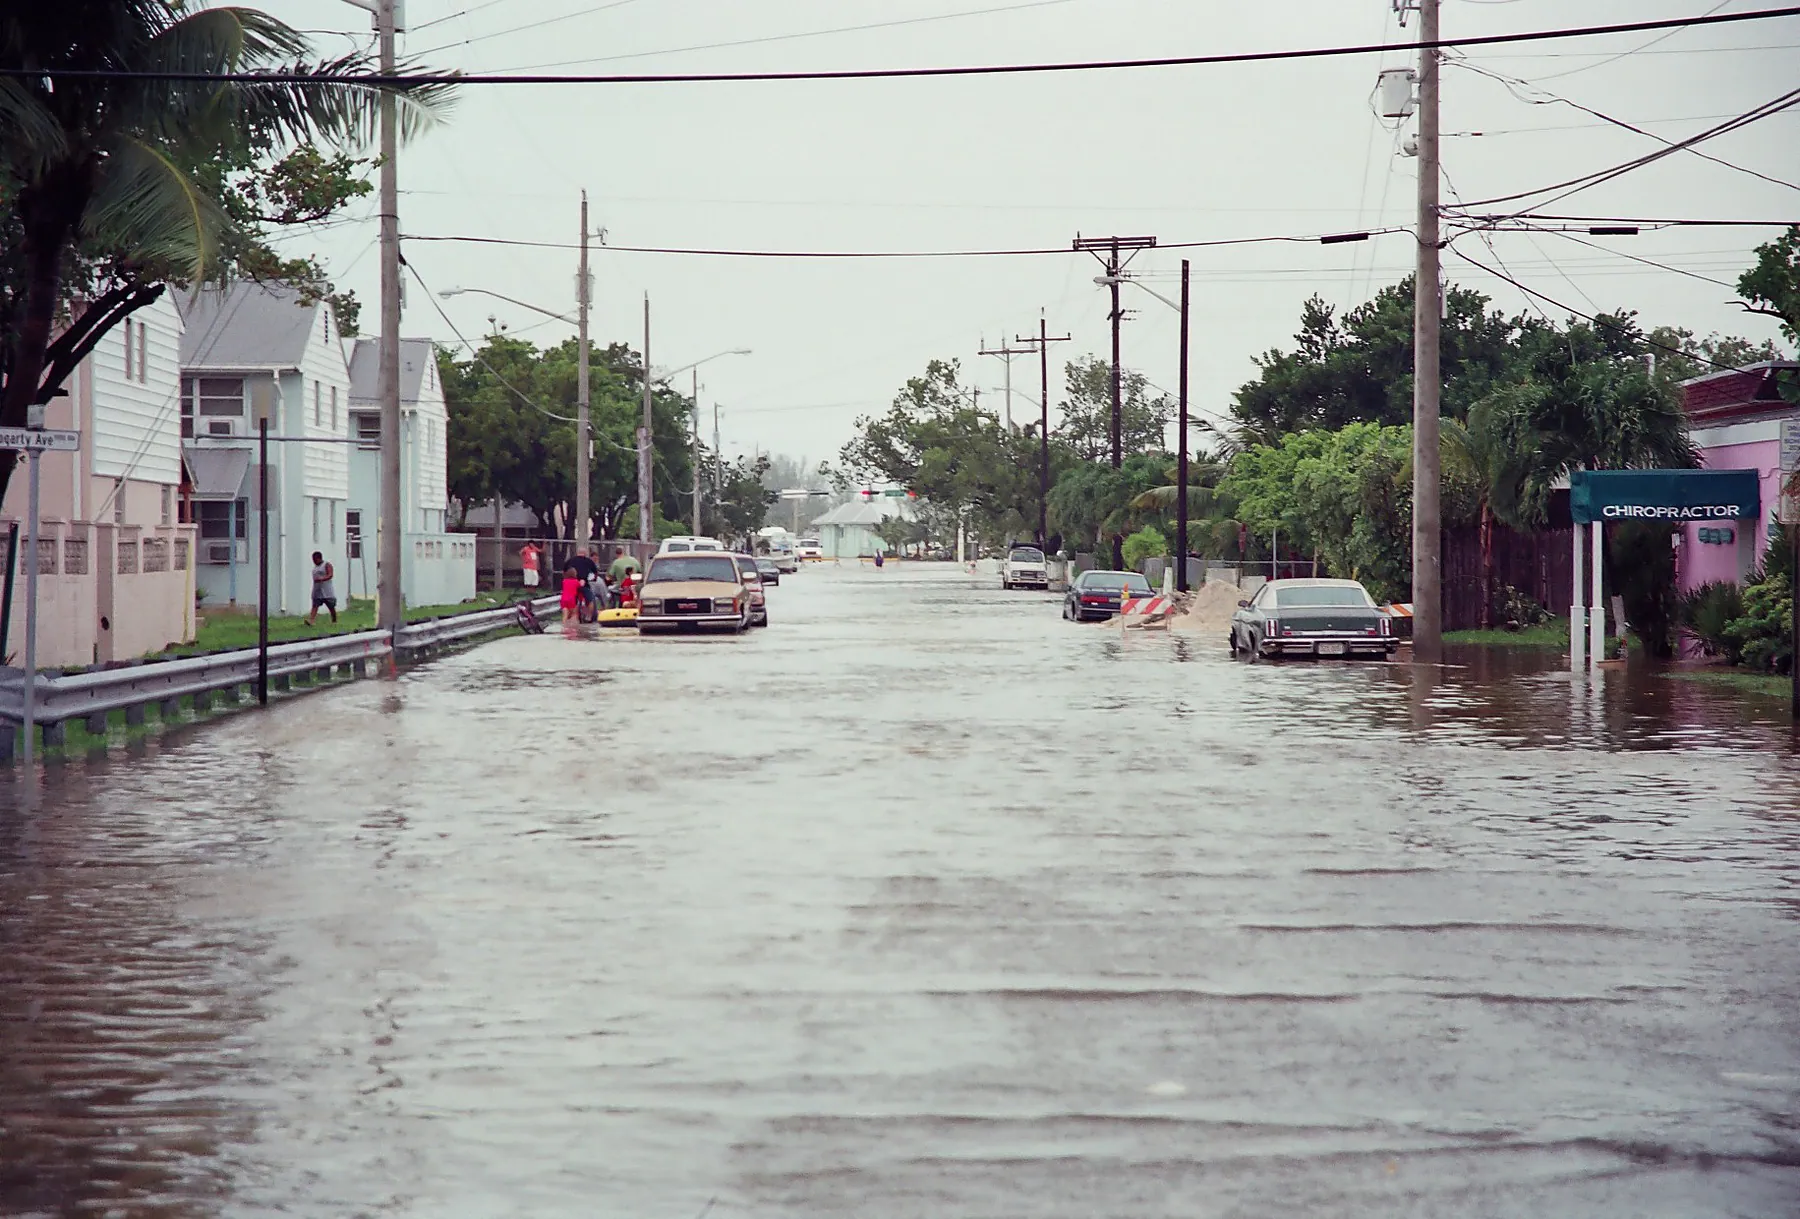 03
A standard homeowners policy does not cover flooding. Flood is a separate policy, from the National Flood Insurance Program or a private insurer, and an NFIP policy usually takes 30 days to start, so it cannot be bought the day a storm is named.
Read the answer →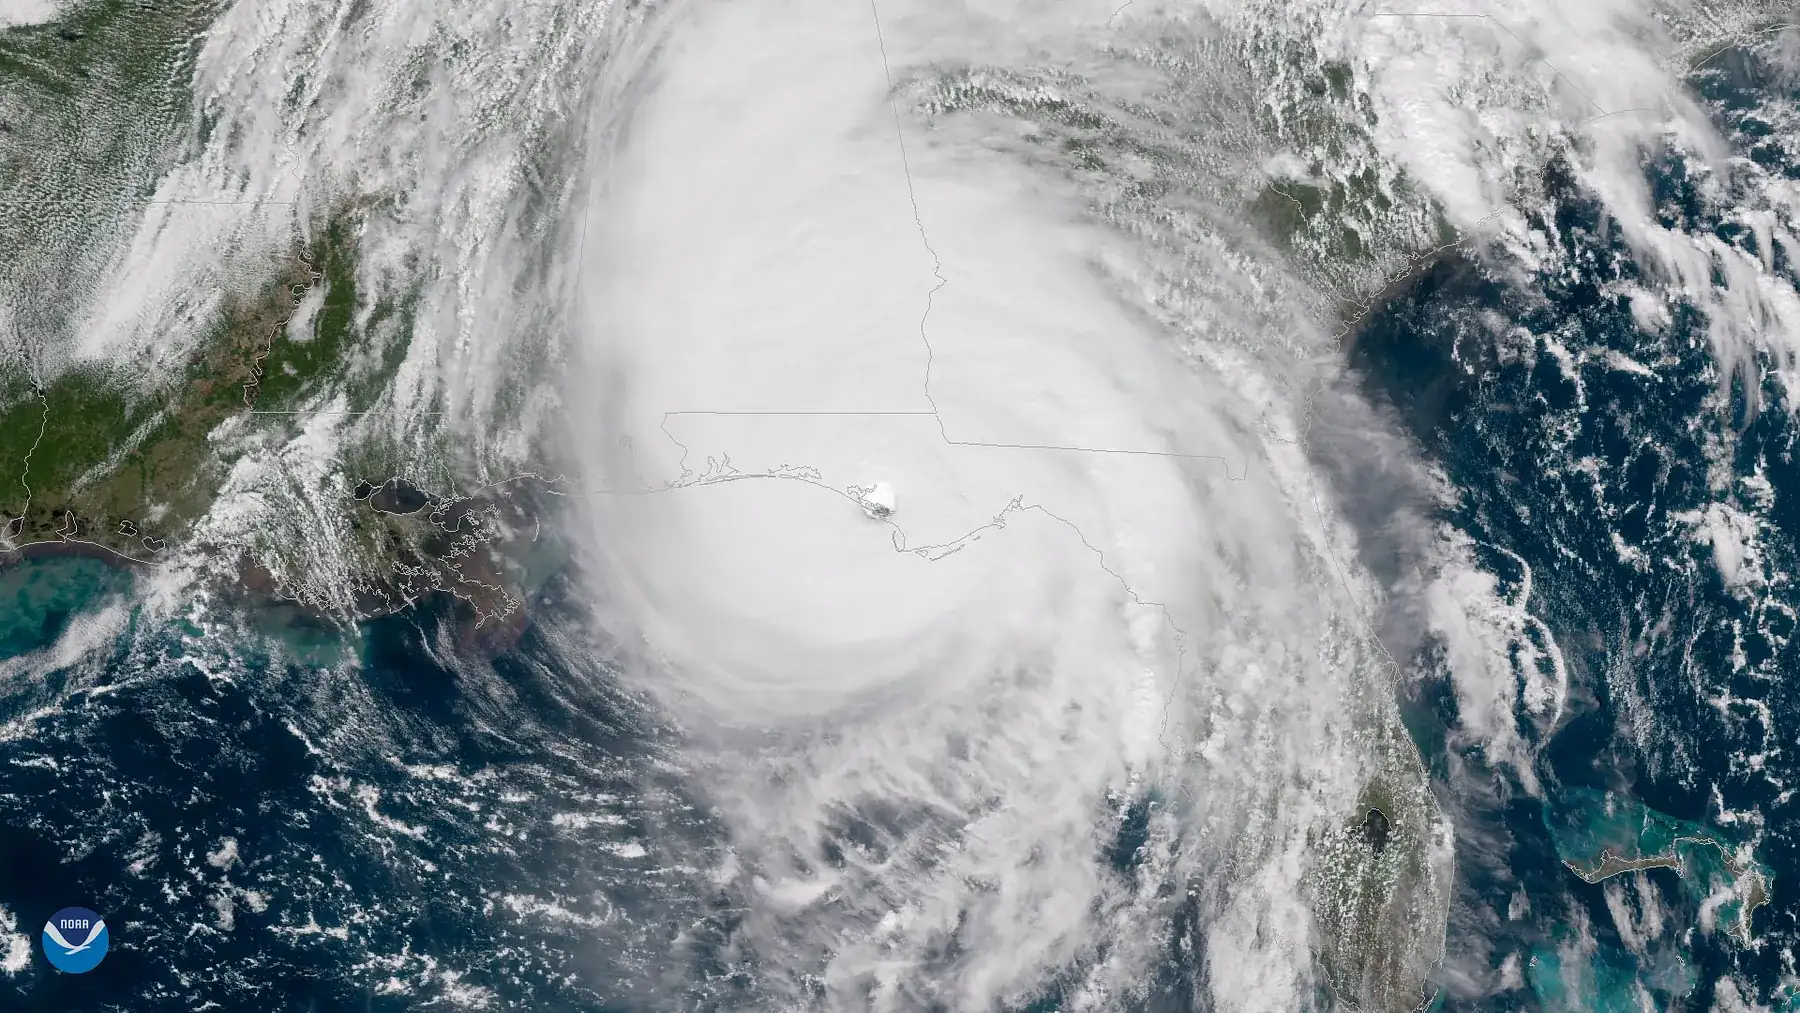 04
Atlantic hurricane season runs from June 1 to November 30. The National Hurricane Center puts its peak on September 10, with most of the activity from mid-August to mid-October.
Read the answer →Have it sized by a load calculation, not by the size of the house.
Florida's sales tax is 6 percent, and most counties add a discretionary sales surtax, which applies only to the first $5,000 of any one item.
A lender works out how much house you can afford from three numbers: your debt-to-income ratio, your credit score, and your down payment, which sets the loan-to-value ratio.
Have a different question? Ask 1stFlorida →