Insurance · Brevard County
Sunshine Shield Insurance
Daniel Cross · Independent insurance agent · Fictional demonstration
Florida insurance is not like insurance anywhere else.
Getting the house insured before you agree to buy it.
Works with people buying in Florida who have never had to insure a house here. Wind, flood and the age of a roof decide more than the house itself does, and all three are answered on the exact address rather than on the town it sits in. The quote comes before the offer, not after it.
Who runs it
Has written Florida policies through several hard seasons, including the years when carriers left the state and people found out what their policy actually said.
The person you speak to first is the person who handles the claim if one ever comes. Nothing is handed to a call center.
What they do
- 01Homeowners cover
The main policy on the house. What is covered, what is excluded, and what the deductible actually is when a storm is named.
- 02Flood, which is separate
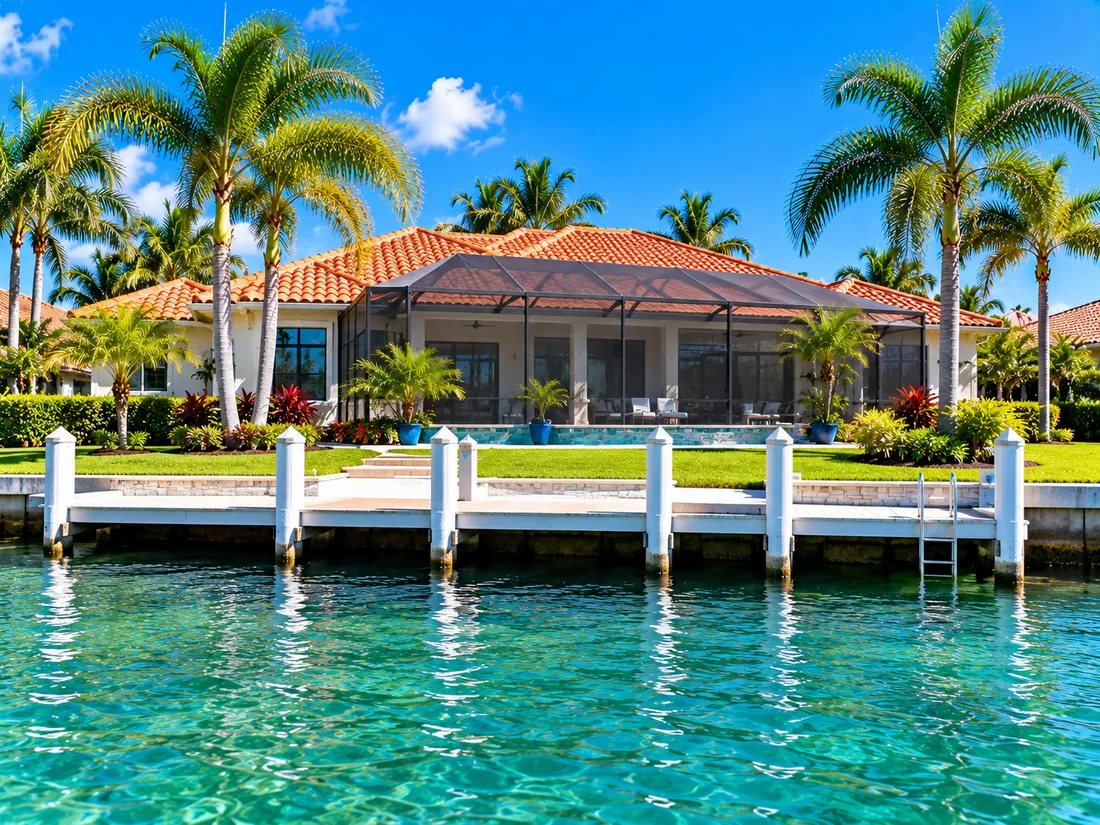
Flood is not part of a homeowners policy in Florida. It is written on its own, it is priced on the address, and a house outside a flood zone can still flood.
- 03Wind and hurricane
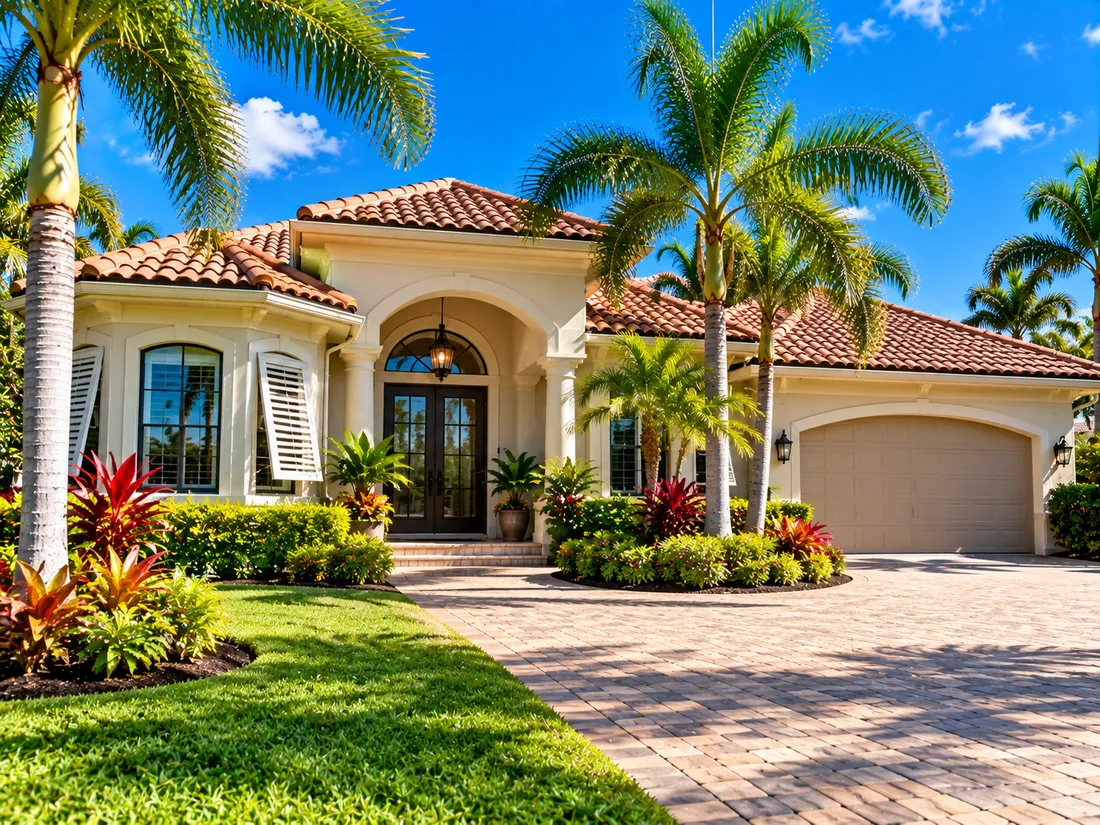
Often a separate deductible and sometimes a separate policy. The roof decides most of it - its age, its material, and whether it has been inspected.
- 04Quoting before you buy
On the actual property, before an offer is signed. A house that cannot be insured affordably is a house you need to know about while you can still walk away.
- 05Condominium and association
What the association's policy covers and what it leaves to you are two different lists, and most buyers see neither until after closing.
- 06Moving your auto cover
Florida has its own requirements and a policy from another state does not simply carry over.
Who it does not suit
It does not suit somebody who wants the cheapest number and will not read what it excludes, anybody who needs cover bound today on a house they have not looked at, or commercial fleets and large business schedules, which are a different business.
Track record
- 2009
- Writing Florida policies since
- Before the offer
- When the quote happens
- Wind, flood, roof
- What Florida cover turns on
How cover gets put in place
- 1The address, not the area
Two houses a mile apart can be quoted very differently. Nothing is estimated from the town.
- 2The roof
Its age and its condition decide more than anything else on the house. This is looked at first.
- 3Flood zone and elevation
Read off the official maps for that parcel, not the neighborhood.
- 4What the quotes actually say
Side by side, with the exclusions and the deductibles read out loud rather than left in the paperwork.
- 5Bound before closing
Cover has to be in place on the day, and lenders will not close without it.
- 6The year after
Florida policies change at renewal more than most. It gets looked at again rather than renewed on sight.
Reach them
- Telephone
- (321) 555-XXXX
- Writes in
- Florida
quotes@sunshineshield.example
sunshineshield.example
Who it suits
This suits people buying a Florida house for the first time, and anyone insuring a house with a roof more than ten years old. It suits buyers near water or in a flood zone, and buyers of a condominium who are not sure what the association covers and what it leaves to them. It suits somebody moving an auto policy in from another state, and anyone renewing who does not understand what changed.
What a policy costs is answered on the actual address, after somebody has looked at the roof - not before.
Call (321) 555-XXXX